
Is my wind and hail deductible a flat amount or a percentage?
Your declarations page tells you. A flat deductible is a set dollar amount, such as $1,000 or $2,500, no matter how big the claim is. A percentage deductible is a share of your dwelling coverage, the amount your home is insured for. The Ohio Department of Insurance (opens in a new tab) puts it plainly: a percentage deductible "is based on the amount the home is insured for, NOT the amount of damage to the home."
How do I figure a percentage deductible?
Multiply your dwelling coverage by the percentage.
- Insured for $250,000 with a 1% deductible: $2,500
- Insured for $250,000 with a 2% deductible: $5,000
- Insured for $350,000 with a 2% deductible: $7,000
Say a storm does $14,000 of covered damage to a home insured for $250,000 with a 2% deductible. You pay the first $5,000. The claim covers the other $9,000, less any depreciation if you have an actual cash value policy.
Where do I find my wind and hail deductible?
On your declarations page, the summary at the front of your policy. Look for a deductible line that names wind and hail (some say windstorm or hail), next to the deductible for all other perils. If you see a percentage, multiply it by the dwelling coverage on the same page.
Not sure what yours says? Email your declarations page to aub@hhrdayton.com and we'll do our best to tell you. We're not an insurance agent or an adjuster, so your agent has the final word.
What if the damage costs less than my deductible?
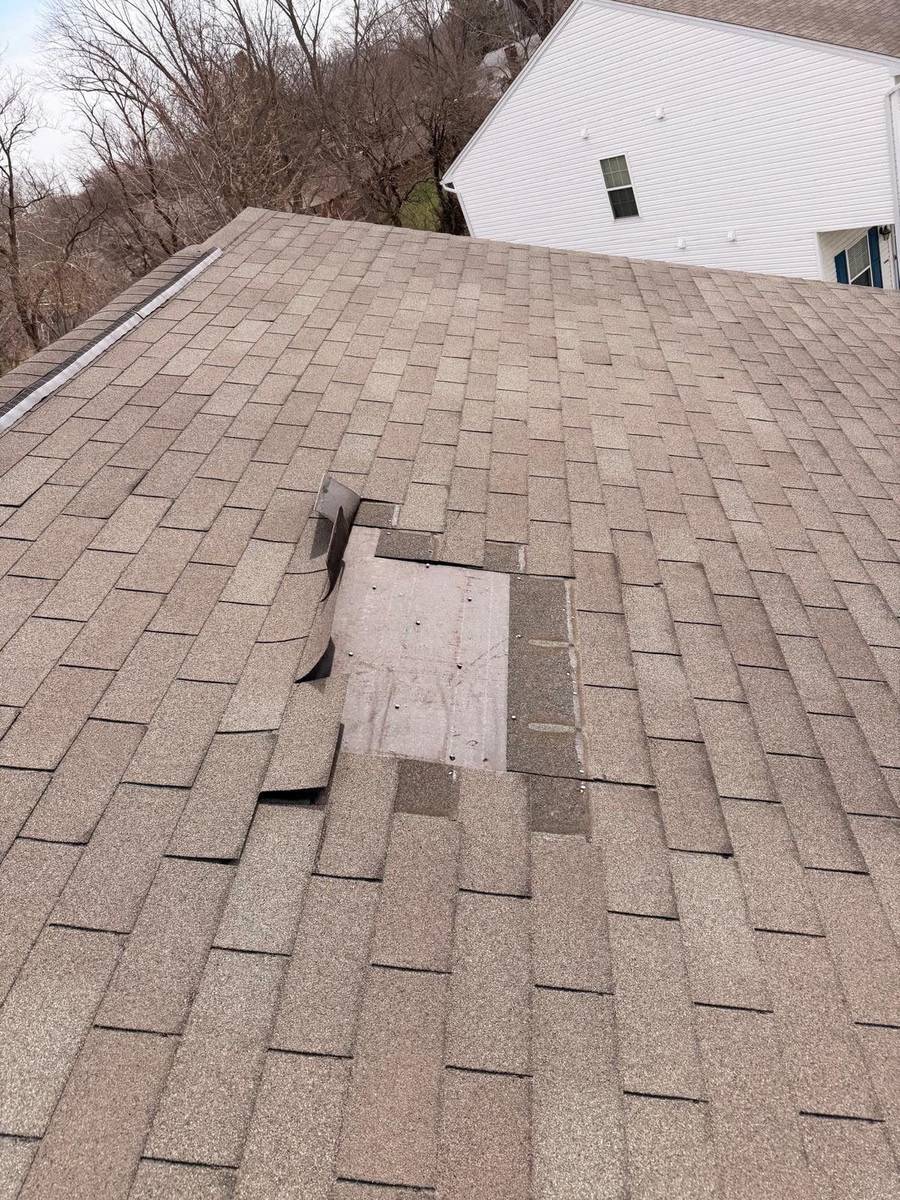
Then the claim pays nothing for that damage, and the repair is yours. That's why we inspect first. Our free roof inspection checks the entire property from the ground, then the whole roof, and we tell you what we see. If the damage is small, a repair may cost less than your deductible. If the storm did real damage, a claim is what the policy is for.
Do I have to pay my deductible on a roof claim?
Yes. Your deductible is your share of the claim under your policy, and you pay it. We never waive a deductible. Once the claim is approved, you pay your deductible, and we build your roof to the Helping Hands Roofing Standard. Our goal is that your out-of-pocket expense for the claim work doesn't exceed your deductible. Upgrades the claim doesn't cover go on a separate contract. If the deductible is hard to cover all at once, financing is available.
Why is my wind and hail deductible so high?
Because a percentage grows with your insured amount. When the amount your home is insured for goes up, a 1% or 2% deductible goes up with it, even though the percentage on the page never changed. Ask your agent what deductible options your insurer offers.
What else should I check on my declarations page?
Two more lines matter on a roof claim:
- Replacement cost value policy or actual cash value policy. An actual cash value policy takes off depreciation for the roof's age and condition.
- Code coverage, sometimes labeled "ordinance and law." It pays for building code items your roof never had. Without it, those items can come out of your pocket on top of the deductible.
More on both: How to Get Insurance to Pay for a Roof Replacement.
Jobs behind this article

Storm damage on your roof?
Call 937-215-8663 for a free roof inspection. We document the damage, help you open the claim and meet your adjuster. Storm damage roofing in Dayton
